
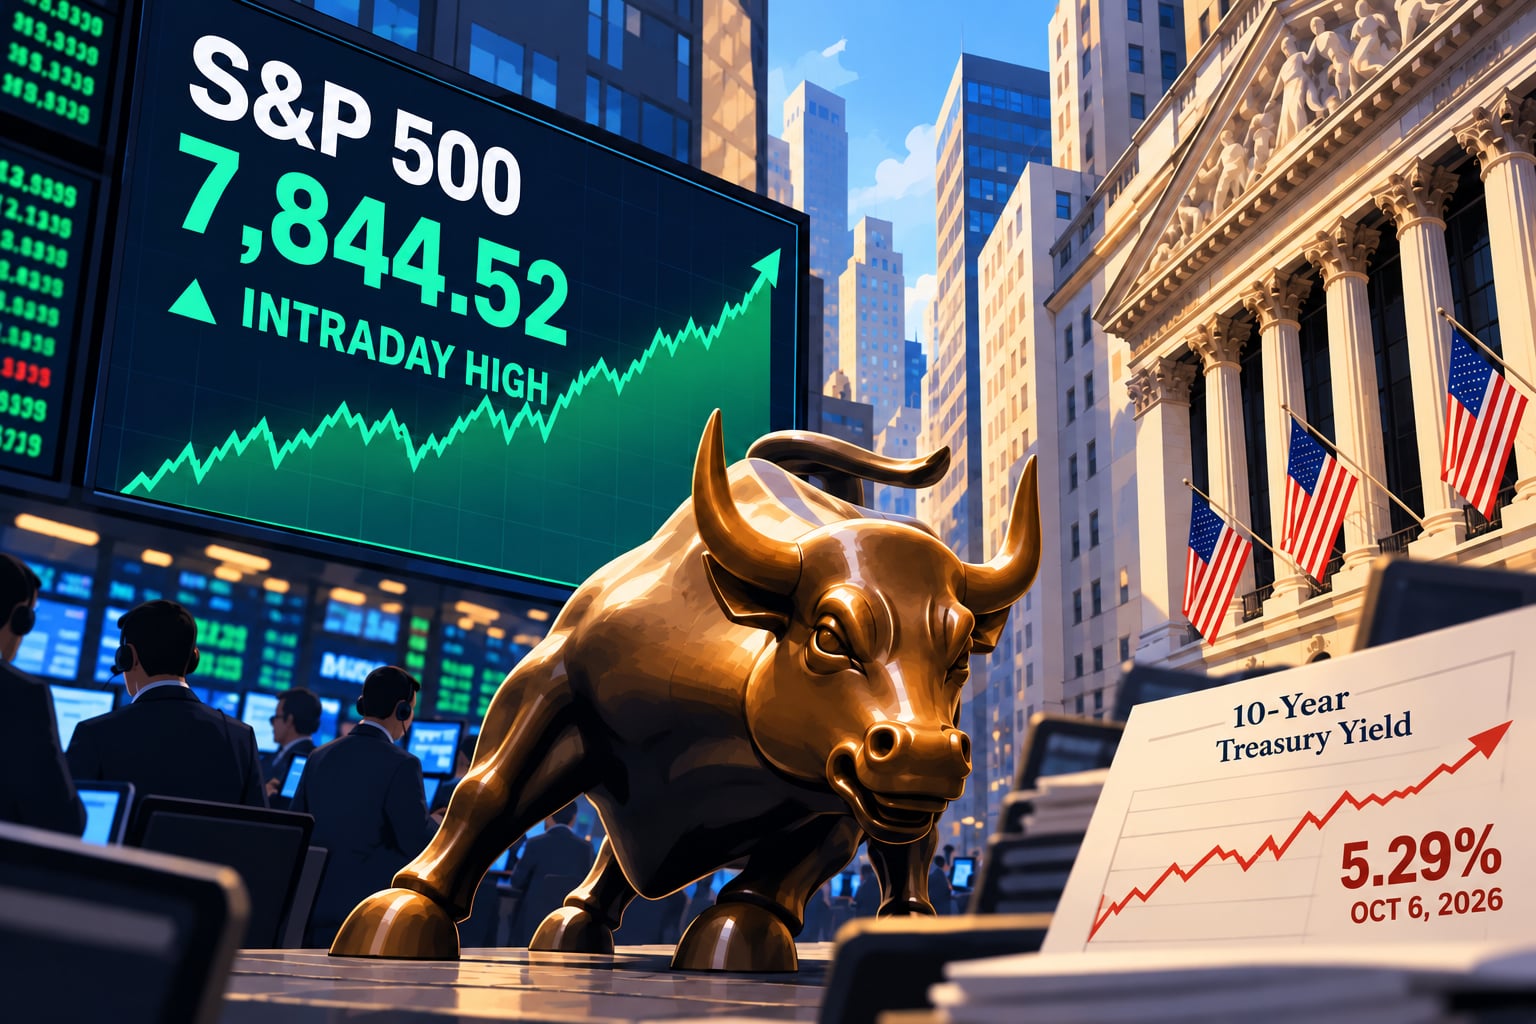
The S&P 500 reached a new intraday record above 7,830 on Tuesday, October 6, as gains in technology and artificial intelligence stocks outweighed pressure from elevated borrowing costs.
Google Finance data shows that the benchmark rose about 0.7% during the session and reached its first intraday record in almost two months. The advance followed a record close for the Nasdaq Composite on Monday, with renewed enthusiasm for AI helping lift the largest technology companies.
The record described here is an intraday high, rather than a confirmed record closing level. Google Finance's October 6 quote, timestamped 1:24:55 p.m. Eastern, listed a session high of 7,844.52. At that snapshot, the index stood at 7,822.48, up 0.62%, showing that it had pulled back from its earlier peak.
Yields ease after a sharp climb
Stocks gained even as Treasury yields remained elevated. Data from October 6 report put the 10-year Treasury yield at 5.29%, below Monday's reported peak of 5.35%.
The headline's comparison with 2002 refers to the recent peak in yields, rather than a new high reached on Tuesday. Five days ago, the 10-year yield touched 5.34%, its highest level since 2002, before retreating later that day.
The distinction matters: Tuesday's equity record came as yields were easing, after the bond sell-off had already driven borrowing costs to unusually high levels.
The 10-year Treasury yield influences financing costs across the economy, including mortgages. Higher yields can weigh on stocks by increasing borrowing costs and making bonds more competitive with equities.
Technology leads an uneven rally
The headline index's recovery has not been shared evenly. According to data from Google Finance, technology was the only sector to gain over the preceding month, while real estate, financials, materials and utilities each fell more than 5%.
Large companies have an outsized influence on the S&P 500 because it is weighted by market value. Nvidia represented more than 8% of the index and had gained 6% during October, giving the benchmark a significant lift.
Other measures showed a less complete recovery. An equal-weight version of the S&P 500 remained more than 4% below its mid-August record, while the Dow Jones Industrial Average was roughly 5% below its early-August peak.
The result was a record for the benchmark alongside continued weakness in parts of the wider market. The key question for the rally is whether gains broaden beyond the technology leaders while financing costs remain elevated.