

Anthropic could reach the public market with a valuation approaching $2 trillion and still struggle to borrow on investment-grade terms. Blackstone has reportedly warned investors that the Claude maker may receive a speculative-grade credit rating after its IPO, despite the money and attention surrounding the listing.
The warning concerns what Anthropic might be rated, rather than a new rating announced by an agency. It also leaves two different questions for investors: how much they would pay to own the company's future growth, and how comfortable lenders are that it can meet its financial obligations.
Benzinga's October 30 report, summarizing a Financial Times account based on people familiar with the matter, said Blackstone had changed its expectations. It had previously expected Anthropic to obtain an investment-grade rating by year-end. It now expects the company may initially fall below that threshold following the offering.
The reported warning was made to investors involved in the $63 billion chip-financing transaction supporting Anthropic. Blackstone's public announcement of that deal explains why its credit outlook matters to the wider AI buildout.
A $63 billion chip deal sits behind the warning
On October 26, Blackstone, Bank of America, Citi and Morgan Stanley announced a financing structure to buy Broadcom AI accelerators and networking equipment for lease to Anthropic. Deliveries are expected to begin in 2027.
The purchases will go through a separate special-purpose vehicle. The banks are arranging the first-lien financing, while Blackstone is the sole provider of the committed second-lien portion. Those labels describe repayment priority: first-lien lenders have a stronger claim on the collateral than second-lien lenders.
Broadcom is providing residual-value support to the vehicle equivalent to the first-lien financing.
Blackstone President Jon Gray said when the transaction was announced:
The rapidly growing demand for AI is creating an enormous opportunity to finance compute capacity at scale. We're proud to help advance this buildout with Broadcom.
The valuation is still an expectation
As previously reported in Apex's live coverage, the $1.5 trillion to $2 trillion figures circulating around the IPO are investor valuation expectations. Anthropic hasn't announced a final offering price. Its October 26 announcement said the number of shares and price range had not yet been determined.
A below-investment-grade rating would not automatically prevent the IPO. It could, however, make future borrowing more expensive and narrow the pool of potential lenders. Some institutional investors face limits on how much speculative-grade debt they can hold.
That matters because a successful share sale doesn't settle the cost of financing years of computing capacity. The company is building a business that needs substantial infrastructure while its revenue is still growing rapidly.
The $80.7 billion loss needs context
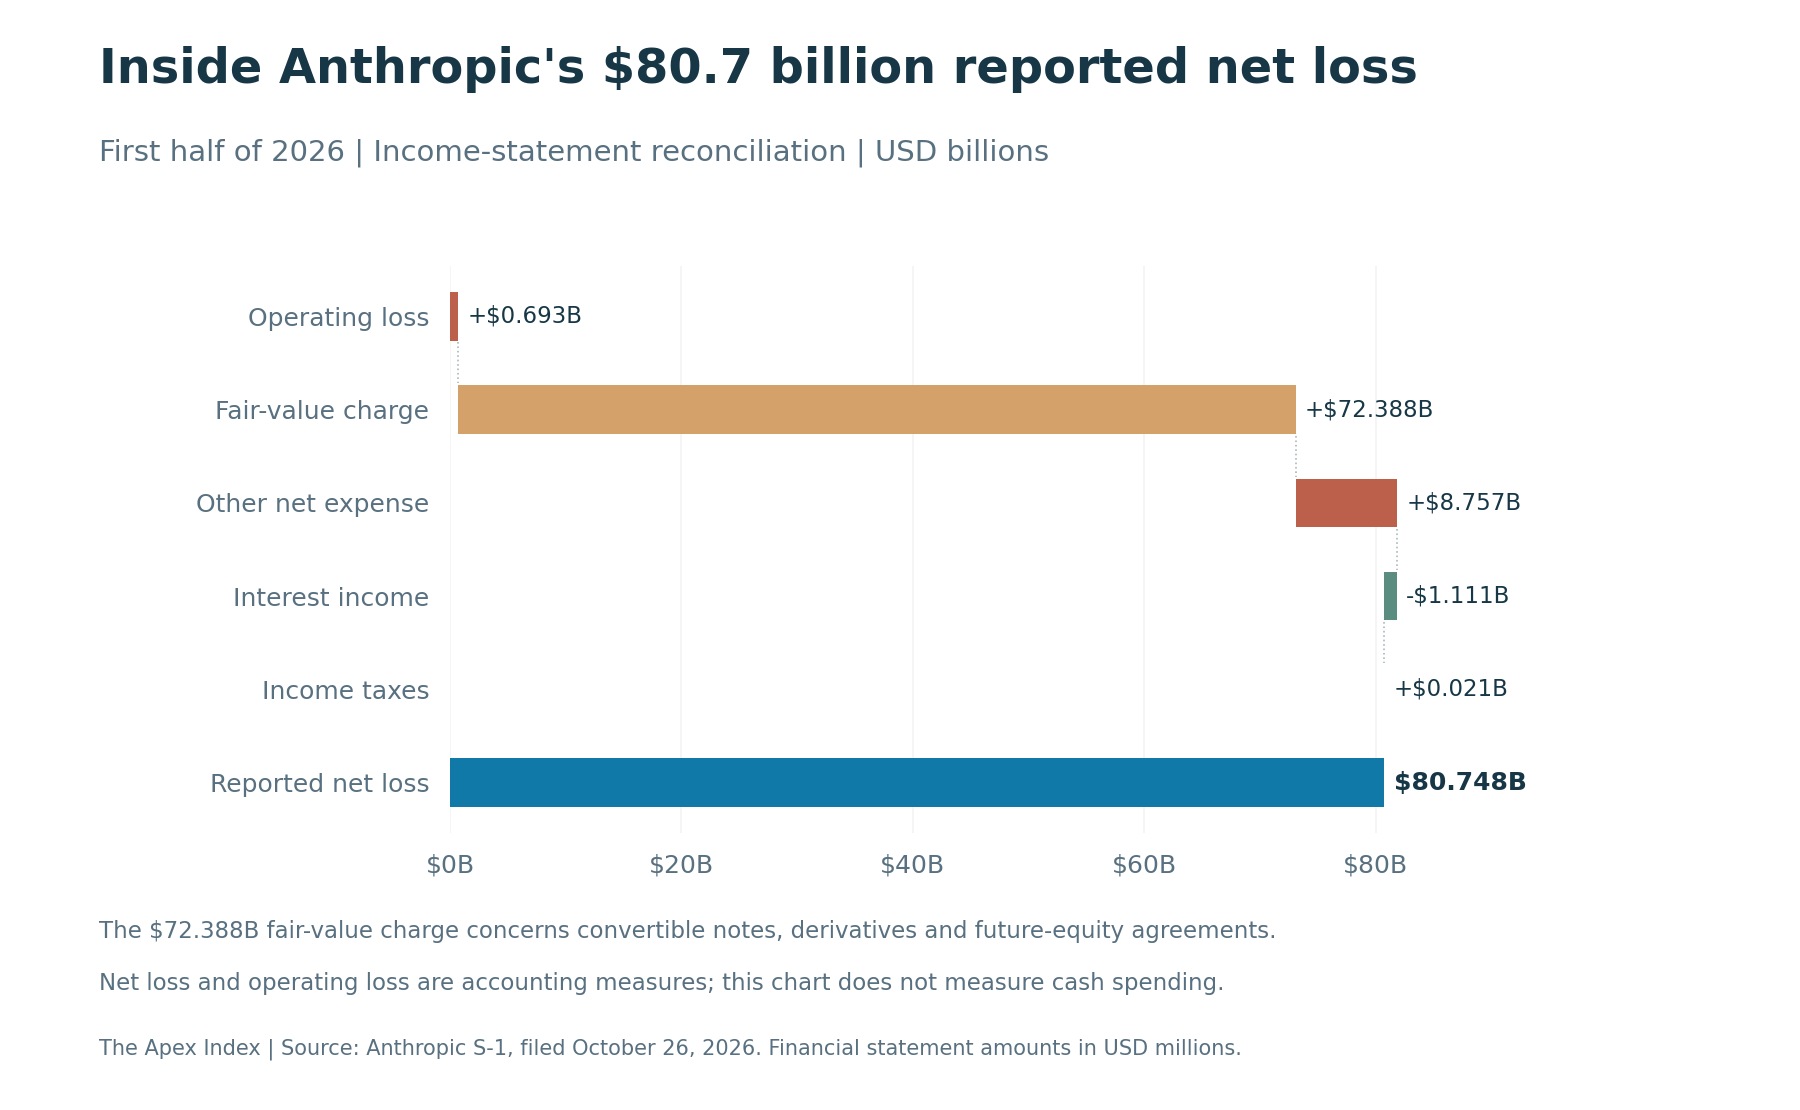
Anthropic's filing reported $16.3 billion in revenue for the first half of 2026 and an $80.7 billion net loss. But $72.4 billion of that loss came from changes in the fair value of convertible notes, derivative liabilities and agreements for future equity.
Its operating loss for the same period was $693 million. The gap is important: the headline net loss includes large accounting adjustments and cannot be read as the amount of cash consumed by day-to-day operations.
The company also reported $112.4 billion in cash and equivalents as of June 30, plus $19.3 billion in short-term investments. Those are historical balance-sheet figures from the prospectus, rather than a new update on its current cash position.
Its own warning about future funding is more direct than the net-loss headline. The prospectus states:
We expect our capital expenditures to increase significantly as we expand our build-out, and we expect these investments to result in significant net cash used in operating and investing activities for the foreseeable future.
Anthropic says the size and timing of those investments remain uncertain and could change materially over short periods. That leaves credit investors assessing the company's future commitments alongside the revenue growth that has drawn interest in its shares.